Ethan Robinson
What to Know About Medicare Open Enrollment
Every year, the Medicare Open Enrollment period, also known as the Annual Election Period (AEP), takes place from October 15th to December 7th. This period allows current Medicare beneficiaries to assess their healthcare needs and revise their coverage accordingly. These dates remain consistent every year.
Medicare Open Enrollment Checklist
Every autumn, the Medicare Open Enrollment Period opens, and millions of Medicare beneficiaries face the important task of evaluating their coverage. But don’t wait until you reach the pharmacy counter only to find out your prescription expenses have doubled. Running from October 15 through December 7, this key window allows you to review, compare, and switch your coverage to help protect your family budget from unexpected healthcare costs.
Review this step-by-step checklist to evaluate your options for 2027 and help keep your healthcare expenses manageable.
Step 1: Gather and Catalog Your Information (September)
Preparation in September sets the foundation for a smooth evaluation process once plan comparison tools open in October. Before comparing new options, take the time to build a clear picture of your current medical profile and upcoming healthcare needs.
- Read Official Notices: Review your plan’s Annual Notice of Change and Evidence of Coverage documents sent by late September. Look specifically for changes to monthly premiums, deductibles, copays, and network restrictions.
- Catalog Doctors and Facilities: Compile an updated list of your primary care physicians, specialists, preferred hospitals, outpatient clinics, and medical supply providers.
- Document All Prescriptions: Write down exact medication names, dosages, daily frequencies, and your preferred retail or mail-order pharmacy.
Step 2: Review and Evaluate Your Current Plan (Late September to October)
Confirming that your primary care physicians and specialists remain in-network for 2027 helps prevent unexpected out-of-pocket costs. Compare next year’s plan structure against your healthcare usage over the past 12 months to help avoid unexpected changes to your care access.
- Evaluate Total Out-of-Pocket Expenses: Look beyond monthly premiums. Calculate estimated annual deductibles, copays, coinsurance rates, and the Maximum Out-of-Pocket limit for Medicare Advantage plans.
- Verify Provider Networks: Confirm that your preferred physicians and medical centers will remain in-network for 2027. Doctor network shifts are common in Advantage plans.
- Audit the Drug Formulary: Verify that your medications remain on your plans drug list. Check for tier shifts, copay increases, or new restrictions like prior authorization or quantity limits.
- Assess Supplemental Benefits: Check for adjustments to extra benefits in Medicare Advantage plans, such as dental allowances, vision hardware, hearing aid coverage, or fitness memberships.
Step 3: Compare Coverage Paths and Options (October 15 to November)
Open Enrollment allows you to evaluate whether your current plan setup still aligns with your health needs or if an alternative strategy is more suitable. Here are some of your core options:
Original Medicare (Parts A and B) plus Standalone Part D plus Medigap: Offers nationwide doctor freedom without network restrictions. Pair Part A and B with a standalone Part D drug plan, and consider a Medicare Supplement policy to help cover out-of-pocket gaps.
Medicare Advantage (Part C): Combines Part A, Part B, and usually Part D into a single plan managed by private insurers. Often features lower premiums and extra benefits, but restricts care to network providers.
- Use Official Comparison Tools: Log into your secure account at Medicare.gov to enter your medication list and compare total estimated annual expenses across all local Part D and Medicare Advantage plans.
- Check CMS Star Ratings: Review the 1 to 5 star quality and performance ratings published by Medicare for plan customer service, member experience, and clinical care.
- Compare Total Expenses: Consider comparing total estimated annual expenses rather than selecting a plan based on a $0 premium alone. A $0 premium plan with high drug copays or restrictive networks can end up costing significantly more overall.
Step 4: Take Action and Submit Changes (By December 7)
Once you have evaluated your options, completing your enrollment before the December 7 deadline helps maintain seamless coverage continuity when the new year begins.
- Staying With Your Current Plan? If you determine your existing coverage remains suitable, no action is needed. Your plan automatically renews on January 1.
- Switching Plans? Submit your new application online at Medicare.gov, call 1-800-MEDICARE, or enroll directly through the insurance carrier. Enrolling in a new plan automatically disenrolls you from your previous plan.
- Save Written Confirmation: Always record and print your enrollment confirmation number, date submitted, and written receipts for your records.
Step 5: Post-Enrollment and New Year Verification (December to January)
Following up on your application helps facilitate a smooth transition into your new plan on January 1. Reviewing your welcome packet and new coverage card in December helps ensure a seamless transition when your plan takes effect on January 1.
- Verify Welcome Materials: Watch your mail in late December for your new plan membership card, welcome packet, and evidence of coverage manual.
- Notify Healthcare Providers: Show your new insurance card to your doctors and preferred pharmacy at your first visit after January 1.
- Update Payment Authorizations: Adjust automatic bank transfers or Social Security premium withholding if your monthly plan payment amounts or insurance providers have changed.
Aligning Your Healthcare Coverage with Your Financial Plan
Healthcare costs can be one of the largest and most unpredictable expenses in retirement, making your choice of Medicare coverage a foundational element of your overall wealth management strategy. Selecting the right combination of premiums, deductibles, and out-of-pocket maximums might seem like a lot of work, but it can help you protect your long-term income streams, preservation goals, and tax efficiency. You don’t have to navigate your Medicare options alone. Schedule a personalized consultation with our team today to review your current options and help align your healthcare strategy with your long-term financial goals.
Sources:<br>https://www.medicare.gov/health-drug-plans/open-enrollment
https://www.humana.com/medicare/medicare-resources/medicare-open-enrollment
https://www.medicare.gov/publications/10050-medicare-and-you.pdf
We do not offer every plan available in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Assistance Program (SHIP) to get information on all of your options. This material is not endorsed by or affiliated with the Social Security Administration, CMS, or any government agency. Investment advisory and financial planning services offered through Simplicity Wealth, LLC, an SEC-registered investment adviser. Insurance services offered through affiliated entities. Simplicity Wealth, LLC is not affiliated with any government agency or Medicare program. This material is provided for educational and informational purposes only and should not be construed as individualized investment, tax, or legal advice. Consult your personal tax professional or financial advisor regarding your specific situation. The source(s) used to prepare this material is/are believed to be true, accurate and reliable, but is/are not guaranteed. 5857975-0826
Financial Planning Month: An Overview
Financial Planning Month is celebrated every year in October. It is designed to raise awareness about the importance of creating a comprehensive financial plan. Launched by financial professionals globally, this initiative aims to encourage individuals to pay closer attention to their financial health, make necessary adjustments, and create a plan to guide them.
6 Quick Ways to Observe Financial Planning Month

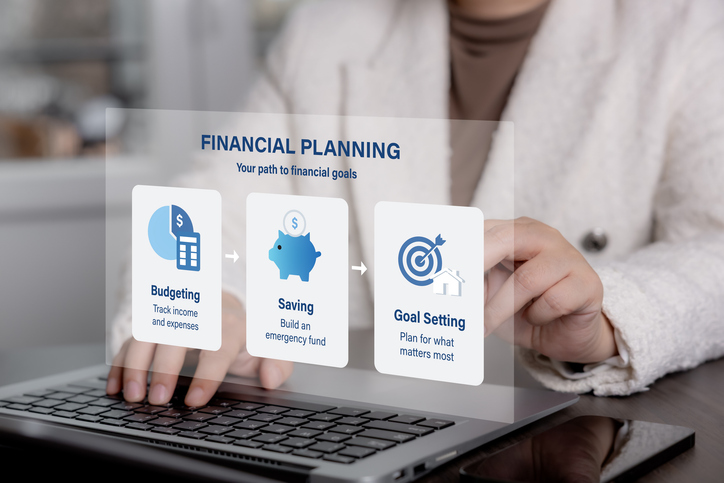
October is recognized as Financial Planning Month, an annual event dedicated to planning for an independent financial future. And while we focus on this topic all year long (and enjoy it!), we get that it might not be the most exciting thing to celebrate. October definitely has more exciting things happening, like pumpkin spice everything, cardigan and cozy scarf weather, and setting out Halloween décor, but if you throw a little financial planning into the mix this month, you could help set your strategy on track for your future.
Let’s take a look at some quick steps you can take to help align your finances with your retirement goals.
1. Do a Quick Financial Check-In
Take 10 minutes to scan your last two months of credit card statements. Are you still paying for a gym you haven’t visited since spring? A streaming service you watched one show on eight months ago? Are you spending too much money eating out?
Consider canceling those ongoing charges, taming any out-of-control spending habits, and rerouting those funds toward a goal you care about.
2. Prepare for Holiday Spending
Speaking of out-of-control spending, November and December have a sneaky way of wrecking well-intentioned budgets. Instead of reacting when the credit card bill arrives in January, set your boundaries now. Decide on an all-in figure for gifts, travel, and festivities and stick to it!
3. Review Year-End Strategies
Are you on track to maximize your retirement contributions this year? Do you need to take a Required Minimum Distribution (RMD)? Are there any charitable gifts or donations you’d like to make during this tax year? Ask your financial professional if there are any moves you should be making now to take advantage of tax-deductible strategies before December 31st arrives.
4. Check on Your Safety Net
Life happens, and sometimes it isn’t financially pretty. Having cash on hand keeps surprise expenses from turning into major setbacks. Check whether you have 3 to 6 months of essential living expenses in an accessible account, just in case you run into an unexpected bump in the road.
5. Increase Your Financial Literacy
Expanding your understanding of financial concepts and terminology can be a fun and engaging way to participate in Financial Planning Month. Many online resources, such as webinars, podcasts, eBooks, and articles, provide valuable information on different aspects of financial planning. Use this month to educate yourself on budgeting, saving, investing, tax strategies, estate planning, risk management, or anything that interests you in the financial world.
6. Revisit Your Goals
We get that financial planning isn’t super exciting. Not many people are thrilled by budgets and tax planning. But there is a part of this process many people enjoy: directing your money toward what makes you genuinely happy!
So, take some time to revisit your goals and think about what you’re actually saving for. Is it a trip abroad? Retiring at 60? Starting a business?
When your money is aligned with your personal values, spreadsheets stop feeling restrictive and start feeling like a roadmap to your real goals.
Turning Small Moves Into Big Milestones
Setting up a financial plan doesn’t have to be overwhelming, and you definitely don’t have to figure it all out alone. Whether you want to fine-tune an existing strategy or start building one from scratch, small steps taken today can pave the way for a more confident tomorrow. Reach out to our team today to schedule a financial check-in!
This information is provided as general information and is not intended to be specific financial guidance. Before you make any decisions regarding your personal financial situation, you should consult a financial or tax professional to discuss your individual circumstances and objectives.
SWG 5858772-0826
6 Quick Ways to Observe Financial Planning Month
October is recognized as Financial Planning Month, an annual event dedicated to planning for an independent financial future. And while we focus on this topic all year long (and enjoy it!), we get that it might not be the most exciting thing to celebrate. October definitely has more exciting things happening, like pumpkin spice everything, cardigan and cozy scarf weather, and setting out Halloween décor, but if you throw a little financial planning into the mix this month, you could help set your strategy on track for your future.
Let’s take a look at some quick steps you can take to help align your finances with your retirement goals.
1. Do a Quick Financial Check-In
Take 10 minutes to scan your last two months of credit card statements. Are you still paying for a gym you haven’t visited since spring? A streaming service you watched one show on eight months ago? Are you spending too much money eating out?
Consider canceling those ongoing charges, taming any out-of-control spending habits, and rerouting those funds toward a goal you care about.
2. Prepare for Holiday Spending
Speaking of out-of-control spending, November and December have a sneaky way of wrecking well-intentioned budgets. Instead of reacting when the credit card bill arrives in January, set your boundaries now. Decide on an all-in figure for gifts, travel, and festivities and stick to it!
3. Review Year-End Strategies
Are you on track to maximize your retirement contributions this year? Do you need to take a Required Minimum Distribution (RMD)? Are there any charitable gifts or donations you’d like to make during this tax year? Ask your financial professional if there are any moves you should be making now to take advantage of tax-deductible strategies before December 31st arrives.
4. Check on Your Safety Net
Life happens, and sometimes it isn’t financially pretty. Having cash on hand keeps surprise expenses from turning into major setbacks. Check whether you have 3 to 6 months of essential living expenses in an accessible account, just in case you run into an unexpected bump in the road.
5. Increase Your Financial Literacy
Expanding your understanding of financial concepts and terminology can be a fun and engaging way to participate in Financial Planning Month. Many online resources, such as webinars, podcasts, eBooks, and articles, provide valuable information on different aspects of financial planning. Use this month to educate yourself on budgeting, saving, investing, tax strategies, estate planning, risk management, or anything that interests you in the financial world.
6. Revisit Your Goals
We get that financial planning isn’t super exciting. Not many people are thrilled by budgets and tax planning. But there is a part of this process many people enjoy: directing your money toward what makes you genuinely happy!
So, take some time to revisit your goals and think about what you’re actually saving for. Is it a trip abroad? Retiring at 60? Starting a business?
When your money is aligned with your personal values, spreadsheets stop feeling restrictive and start feeling like a roadmap to your real goals.
Turning Small Moves Into Big Milestones
Setting up a financial plan doesn’t have to be overwhelming, and you definitely don’t have to figure it all out alone. Whether you want to fine-tune an existing strategy or start building one from scratch, small steps taken today can pave the way for a more confident tomorrow. Reach out to our team today to schedule a financial check-in!
This information is provided as general information and is not intended to be specific financial guidance. Before you make any decisions regarding your personal financial situation, you should consult a financial or tax professional to discuss your individual circumstances and objectives.
SWG 5858772-0826
What Is Liquidity, and Why Is It So Important in Retirement?
Liquidity, in financial terms, refers to the ease with which an asset can be converted into cash without affecting its market price. More liquid assets, such as savings accounts or money market funds, can be quickly sold or accessed for cash. In contrast, less liquid assets, like real estate or certain investment strategies, may take longer to sell and may require a price drop to expedite the process.
Managing Taxes in Your Estate Plan

Transitioning into retirement often involves shifting your focus from building your assets to distributing them, but the methods used to accumulate assets differ from the strategies required to help generate sustainable income and manage spending. During this phase, managing taxes and maintaining access to liquidity become important priorities. For families who want their life’s work to directly benefit children and grandchildren, an efficient wealth transfer can help them reach that goal.
Managing Potential Estate Tax Implications
One notable challenge in wealth distribution involves navigating changing tax regulations. These rules can create unexpected tax considerations for heirs who inherit IRAs. Relying entirely on traditional retirement accounts to transfer wealth may leave beneficiaries with limited flexibility when managing those distributions.
While federal taxes receive significant attention, several states enforce state-level estate taxes with exemption limits starting around $1 million. Because of these lower thresholds, state estate taxes can apply to more families than the federal estate tax. At the federal level, the exemption threshold stands at $15 million for individuals and $30 million for married couples. Federal estate tax rates apply to assets exceeding those thresholds and range from 18% to 40%.
Working with a qualified tax and financial professional can help you evaluate suitable strategies for your estate. A thoughtful approach focuses on providing flexibility and options to support your financial goals.
Multi-Year Roth Conversion Strategies
A financial professional may suggest a multi-year Roth conversion plan. This strategy involves moving wealth from tax-deferred accounts to tax-free accounts over several years, typically when you are in a lower tax bracket. By paying taxes on IRA assets systematically at known current rates, you can help manage future tax exposure for your beneficiaries. When structured appropriately, future withdrawals by your heirs may be tax-free.
Trust and Beneficiary Alignment
An important part of estate planning involves reviewing asset titles and beneficiary designations to help facilitate efficient wealth transfer; otherwise, your assets may not go where you want them to. Trusts can assist with estate tax management in specific situations, so here are some things to consider:
- Setting up an irrevocable trust requires transferring control of the designated assets permanently.
- Assets placed in an irrevocable trust belong legally to the trust rather than to you.
- Assets in an irrevocable trust generally do not count toward the overall value of your estate, which may help lower potential estate tax liabilities.
Additionally, a generation-skipping trust allows individuals to transfer assets to grandchildren or later descendants. This structure can help bypass one layer of estate taxation.
Strategic Gifting
Strategic gifting helps preserve wealth by helping reduce the taxable value of an estate. As mentioned earlier, when an individual passes away, the federal government can apply an estate tax of up to 40% on assets that exceed the lifetime exemption limit, and some states impose taxes at lower thresholds. By transferring assets during their lifetime, such as using the annual gift tax exclusion ($19,000 per recipient), funding education accounts, or passing on investment growth potential, retirees can help reduce their taxable estate. This approach helps move principal assets and potential future growth outside the taxable estate, allowing heirs to receive more of the estate while you get to see your family receive support today.
Beyond traditional investment accounts, permanent life insurance products may offer additional flexibility. Rather than serving solely as a death benefit, suitable permanent life insurance policies can offer access to tax-efficient cash value during your lifetime while supporting wealth transfer goals.
Planning Your Retirement Approach
The tax rules around wealth transfers can be complex. Fortunately, you do not have to navigate them alone, as we can discuss several strategies to help structure transfers. You may consider strategies like life insurance to help manage wealth transfers and potential tax obligations, or you might consider other options. No matter the case, our goal is to help you support your heirs to help you feel more confident in your estate, and that means strategically managing your assets while you’re still alive.
A strategy tailored to your specific goals can help address potential tax risks and financial uncertainties that cloud your vision of retirement. Consider taking a proactive approach and call us so we can help to better position your estate to support your family for years to come.
Sources:
https://www.investopedia.com/articles/retirement/07/reduce-estate-tax.asp
https://www.fidelity.com/learning-center/personal-finance/how-to-avoid-estate-taxes
https://smartasset.com/estate-planning/how-to-avoid-estate-taxes-with-trusts
This material is designed to provide general information on the subjects covered. Pursuant to IRS Circular 230, it is not intended to provide specific legal or tax advice and cannot be used to avoid penalties or to promote, market, or recommend any tax plan or arrangement. You are encouraged to consult your personal tax advisor or attorney. The source(s) used to prepare this material is/are believed to be true, accurate, and reliable, but is/are not guaranteed. Policy loans and withdrawals will reduce available cash values and death benefits, and may cause the policy to lapse or affect any guarantees against lapse. Additional premium payments may be required to keep the policy in force. Tax laws are subject to change, and you should consult a tax professional. SW5811615-0826
The Difference Between Short-term and Long-term Tax Planning
Understanding taxation is a crucial aspect of personal and business financial management. Two common approaches to optimizing one’s tax situation are short-term and long-term tax planning. The fundamental distinction between these two methods lies in the time frame and strategy employed. Investors can benefit from understanding the difference as they work with financial and tax professionals toward financial independence.
Is Your Retirement Income Weatherproof?
For decades, your daily ritual may have involved morning coffee, the commute, demanding work schedules, and, of course, saving for retirement. As retirement approaches, you may have built a financial plan designed around your long-term goals and desired lifestyle. However, given ongoing economic news and market volatility, it is natural to evaluate how fluctuations in the market may impact your retirement strategy.
The market forecast is like a weather report. A chance of rain doesn’t mean you cancel everything; rather, it means you prepare with an umbrella or jacket. Because market fluctuations are a natural part of investing, implementing risk management strategies can help align your portfolio with your retirement timeline and financial goals.
If your retirement strategy depends primarily on withdrawing funds directly from a traditional retirement account or growth-focused portfolios regardless of market conditions, you are not alone. But relying on fluctuating portfolio values to cover daily expenses might create unnecessary uncertainty that can negatively impact your long-term retirement savings.
The Potential Storm: Sequence of Returns Risk
During your wealth accumulation years, market downturns mean you may acquire shares at lower prices. But the moment you transition from saving to spending, market downturns reflect a new reality. Enter sequence of returns risk, an important retirement planning consideration that can affect portfolio sustainability during the early years of retirement.
Imagine retiring during a period of significant decline. If you need $80,000 this year to cover travel, healthcare, and living expenses, while your equity portfolio drops by 20%, you may need to sell more shares to generate the same amount of income. This can reduce the assets available to benefit from future market growth.
The impact can be significant. Early investment losses combined with ongoing withdrawals may affect the long-term sustainability of a portfolio, even when long-term average market returns appear favorable.
Weathering the Storm
Market fluctuations are a normal feature of the economic landscape, and preparation can play an important role in navigating changing conditions. A prepared financial architect doesn’t attempt to predict market cycles; instead, it focuses on creating a framework designed to address potential challenges as they arise.
Rather than reacting emotionally to market changes, a well-structured retirement foundation helps address your monthly income needs during short-term market fluctuations. By addressing sequence risk structurally, you may be better positioned to manage income needs and navigate periods of market volatility with greater confidence.
The Three-Bucket Liquidity Strategy
To help mitigate sequence risk, many financial professionals use a structural framework known as the Three-Bucket Liquidity Strategy. This approach categorizes your wealth not merely by asset class, but also by horizon and purpose:
- Bucket 1: Now (Cash & Liquidity — Years 1–3)— Lower volatility, highly liquid assets intended to cover immediate living expenses and short-term goals. Designed to reduce exposure to stock market volatility.
- Bucket 2: Soon (Income & Stability — Years 4–8)—Balanced, yield-generating instruments designed to help support Bucket 1 over time while seeking to manage principal and interest rate risks.
- Bucket 3: Later (Growth & Upside — Years 9+)—Long-term equities and growth assets that have a longer time horizon to recover from market dips and seek long-term growth potential.
When the stock market takes a sudden downturn, you may choose not to draw from Bucket 3. You may allow your growth assets to remain, allowing additional time to potentially recover from market declines.
The Volatility Buffer: Your 2-to-3-Year
A key component of Bucket 1 lies in an important mechanism called the volatility buffer. This is a dedicated 2-to-3-year liquid reserve maintained outside of volatile equity markets.
The volatility buffer acts as a financial shock absorber, helping make sure you don’t sell discounted equity shares to buy groceries, pay property taxes, or fund a trip.
If a market contraction lasts a couple of years, your volatility buffer helps reduce the impact. You can potentially draw income from your conservative reserve while equity markets recover. Once markets rebound and reach new highs, your financial advisor can help guide you toward refilling the buffer. This simple structural rule can help manage the impact of market corrections on your day-to-day budget.
Living the Life You Earned
Retirement should mark the beginning of your life’s most rewarding chapter, not a period of unnecessary financial uncertainty. Building a resilient retirement income plan is about putting structural measures between market volatility and your everyday quality of life.
A tailored three-bucket approach with a resilient volatility buffer could help you finally enjoy your morning coffee knowing your retirement is built to weather any storm. But not all strategies fit every situation, so reach out to us so we can discuss a plan that fits your individual retirement needs.